

A credit card trifecta is a set of three complementary cards from one issuer (or a mix) that combine to cover nearly every spending category while pooling rewards into a single, more flexible currency. Chase’s trifecta wins on simplicity and easy Visa acceptance. Amex’s trifecta pushes for the highest per-dollar value on dining, groceries, and travel, at a steeper combined fee. A mixed trifecta picks the best card from each issuer, trading some simplicity for a higher ceiling. Your spending habits and tolerance for tracking multiple point systems should decide which one fits you.
TL;DR:
- The Chase trifecta offers the best balance between cost, simplicity, and merchant acceptance, especially for moderate spenders who value flexibility.
- The Amex trifecta provides higher rewards on dining, groceries, and travel but involves significantly steeper annual fees and requires diligent credit management.
- A mixed trifecta can maximize category bonuses but demands careful tracking of multiple point systems, transfer partners, and renewal dates.
- For low to moderate annual spending, sticking with a single premium card plus a no-fee backup often yields similar rewards with less effort.
- Success depends on honestly evaluating your spending habits, merchant acceptance, and willingness to track credits, with tools available to optimize your setup.
Table of Contents
- What Is a Credit Card Trifecta and How Do the Three Frameworks Work?
- How Does the Chase Trifecta Work, and What Does It Cost You Net of Credits?
- How Does the Amex Trifecta Work, and When Do Higher Fees Pay Off?
- When Does a Mixed Trifecta Beat a Single-Issuer Setup?
- How Do You Choose the Right Trifecta for Your Spending?
- Sample Math: Chase Trifecta vs. Amex Trifecta for a Real Spender
- When Is a Trifecta Overkill?
- Track Your Trifecta With Savings Grove’s Tools
- Sources
- FAQ
What Is a Credit Card Trifecta and How Do the Three Frameworks Work?
The idea behind a trifecta is straightforward: no single card covers every category well, so you pick three that overlap just enough to fill the gaps. One card usually earns a strong flat rate on everything, another targets specific bonus categories like dining or groceries, and a third acts as the “anchor” that unlocks the best redemption value, usually through airline and hotel transfer partners. Instead of three disconnected reward balances, you’re funneling everything into one pool.
That pooling is what separates a trifecta from just owning three unrelated cards. Chase Ultimate Rewards and American Express Membership Rewards both let you combine points earned on eligible cards into a single account, then redeem them together at the anchor card’s best rate. A no-annual-fee card earning 1.5% cash back on its own is fine. That same card feeding points into a premium travel card’s transfer partners can be worth meaningfully more.
Three frameworks dominate how U.S. rewards optimizers build this setup:
- Chase trifecta: A Sapphire card paired with Freedom Flex and Freedom Unlimited, pooling everything into Ultimate Rewards.
- Amex trifecta: Platinum or Gold paired with a business or catchall Membership Rewards earner, built for outsized dining, grocery, and travel bonuses.
- Mixed trifecta: The strongest card from each issuer, chosen for acceptance, transfer partners, or category strength rather than issuer loyalty.
Each comes with trade-offs. Chase cards run on the Visa network, which merchants accept almost everywhere, and the combined annual fees stay relatively low if you skip the Reserve tier. Amex earns faster in food and travel categories but gets rejected occasionally at smaller merchants and charges more for premium perks. Mixed setups can out-earn either single-issuer option, but you’re juggling two or three separate point balances, two sets of transfer partners, and double the renewal dates to track.
How Does the Chase Trifecta Work, and What Does It Cost You Net of Credits?
The Chase trifecta is the most copied setup in the rewards world because it’s genuinely simple to run. You hold a Sapphire card (Preferred or Reserve), a Freedom Flex, and a Freedom Unlimited, and every point lands in one Ultimate Rewards account. Some people add a Chase Ink business card to the mix once they qualify, since Ink cards earn Ultimate Rewards too and often carry stronger bonus categories for business spending.
The mechanics work like this:
- Freedom Flex earns 5% on rotating quarterly categories (up to a quarterly cap) plus solid rates on dining and drugstores.
- Freedom Unlimited earns a flat 1.5% (often boosted to higher rates in specific categories) on everything else, so nothing falls through the cracks.
- Sapphire Preferred or Reserve acts as the anchor. It doesn’t need to earn the most points. It needs to redeem them at the highest value, since only Sapphire cards can transfer Ultimate Rewards to airline and hotel partners at full value.
Chase’s transfer partners include Hyatt, United, Southwest, British Airways, and Air France/KLM, and Hyatt in particular gets singled out repeatedly as a standout redemption because Hyatt’s award chart tends to price out well below cash rates for mid-tier and luxury hotels.
Here’s what the earning looks like in practice for a household spending a moderate amount a month across categories: dining and travel booked through Chase’s portal earn 2x to 3x with Sapphire Preferred, rotating categories on Freedom Flex (often groceries, gas, or streaming) earn 5%, and the catchall Freedom Unlimited soaks up everything else at 1.5% minimum. A moderate spender can earn tens of thousands of Ultimate Rewards points a year, worth several hundred dollars depending on redemption choices.
On fees, Sapphire Preferred runs a moderate annual fee and typically includes an annual hotel credit through Chase Travel plus other smaller perks. The two Freedom cards carry no annual fee. That puts your total trifecta cost relatively low, and if you use the included credits, your effective annual cost can drop close to zero. Sapphire Reserve costs considerably more but bundles in a much larger travel credit, airport lounge access, and a higher points multiplier on travel and dining, which changes the math for frequent travelers.
Pro Tip: Apply for your Freedom cards before the Sapphire card if you’re building the trifecta from scratch. Chase weighs recent Sapphire bonuses against approval for other Chase products, so sequencing your applications the right way can protect your odds.
Eligibility is where Chase gets strict. The company’s informal “5/24” rule means you’ll likely get denied for a new Chase card if you’ve opened five or more personal credit cards (from any issuer) in the past 24 months. If you’re actively rewards hunting across multiple issuers, apply for your Chase cards first, before that count climbs. A credit score in the high 600s can work for the Freedom cards, but Sapphire approvals get easier the closer you are to 720 and above.
How Does the Amex Trifecta Work, and When Do Higher Fees Pay Off?
The Amex trifecta trades Chase’s low cost for higher earning rates in the categories that matter most to frequent diners and travelers. The typical combo pairs Platinum and Gold with a business or catchall Membership Rewards earner, and the annual fees are considerably steeper across the board.
The role each card plays:
- Amex Gold covers dining and U.S. supermarkets at some of the highest earn rates available on any card, making it the workhorse for everyday grocery and restaurant spending.
- Amex Platinum anchors the setup for travel: elevated earning on flights booked directly with airlines or through Amex Travel, plus lounge access and a long list of statement credits.
- A business or catchall Amex card (Blue Business Plus is a common pick) fills in flat-rate earning on purchases that don’t fit Gold or Platinum’s bonus categories.
Membership Rewards points from all three cards land in one account, and Amex offers more than 20 airline and hotel transfer partners, giving you more redemption paths than Chase, though not always at better rates for any single trip.
For a household spending $3,000 monthly with heavy dining and grocery habits, Gold’s bonus categories alone can generate 4x points on a big chunk of that spend. Add Platinum’s travel bonuses and the catchall card’s flat rate, and an aggressive spender can clear 70,000 to 90,000 Membership Rewards points annually, noticeably ahead of a comparable Chase trifecta for the same spend pattern, assuming dining and groceries make up a real share of the budget.
The fee side is where Amex asks more of you. Gold runs $325 a year, and Platinum sits well above $600. Combined, you’re looking at close to $1,000 in annual fees before any business card cost. Amex offsets this with statement credits: dining credits, Uber Cash, an airline fee credit, and other perks tied to Platinum specifically. Add those up correctly and diligently, and the effective net cost of Platinum can fall by several hundred dollars, though only if you actually use each credit before it expires.
Pro Tip: Set calendar reminders for every Amex credit that resets monthly or quarterly. Statement credits you forget to use are the single biggest reason Amex trifectas end up costing more than they should.
The Amex trifecta earns its keep when your spending genuinely concentrates in dining, groceries, and premium travel, and when you’re organized enough to actually redeem the credits rather than let them lapse. It makes less sense if you shop mostly at big-box retailers or gas stations, since Amex acceptance can be spottier at smaller and independent merchants than Visa’s.
When Does a Mixed Trifecta Beat a Single-Issuer Setup?
A mixed trifecta cherry-picks the strongest card from multiple issuers instead of committing to one ecosystem. A common example: Amex Gold for dining and groceries, Chase Sapphire Reserve for travel redemptions and trip protections, and a third issuer’s flat-rate card, sometimes Capital One or a no-fee cash-back card, for everything that doesn’t fit either.
This approach optimizes for peak value rather than convenience. You’re not settling for Chase’s slightly lower dining multiplier or Amex’s occasionally weaker acceptance. You get Gold’s category strength and Sapphire’s transfer network in the same wallet.
A few things to weigh before going this route:
- You’re managing two separate point currencies, which means tracking two sets of transfer partners, two annual fee renewal dates, and two redemption strategies instead of one.
- Consolidation timing matters. Big transfers to a single airline or hotel program work best around a specific booking, not spread thin across both programs “just in case.”
- Mixed setups reward disciplined trackers. If you’re not the type to check statement credits or compare redemption values before booking, the extra complexity usually erodes any value gained over a simpler single-issuer trifecta.
Mixed setups tend to beat a single-issuer trifecta for travelers with genuinely lopsided spending, heavy on dining and also heavy on premium hotel stays, where no single issuer’s category bonuses cover both well. If your spending is more evenly distributed or you’d rather not think about which point currency to use for which trip, a single-issuer Chase or Amex trifecta will usually get you 80% of the value with half the mental overhead.
How Do You Choose the Right Trifecta for Your Spending?
Start by being honest about how much bandwidth you have for tracking rewards. A trifecta only pays off if you actually use the bonus categories and redeem the credits, not just collect the cards.
Before applying for anything, evaluate:
- Your top three spending categories over the last three months (dining, groceries, travel, gas, everything else).
- Your travel goals, specifically whether you fly and stay at hotels enough to make transfer partners worth learning.
- Merchant acceptance in your area, since Amex acceptance varies more by region and merchant size than Visa’s.
- Your fee tolerance, meaning what you’re comfortable paying upfront before credits offset any of it.
From there, run this four-step process:
- Pull three months of statements and tag every purchase by category. This tells you where a bonus multiplier would actually matter, not where you assume it would.
- Map your top categories to card bonuses across Chase, Amex, and mixed options, using a category spending guide to see which cards reward your actual habits.
- Simulate net value by estimating annual points earned, converting them at a reasonable redemption value, then subtracting combined annual fees minus credits you’ll realistically use.
- Plan your applications with timing in mind. Apply for Chase cards first if you’re near the 5/24 threshold, space out hard inquiries by a few months where possible, and keep utilization under 30% while you’re actively applying.
A quick gut check on approval odds: most issuers pull your full credit report for a new application (a hard inquiry), and stacking several hard inquiries in a short window can shave points off your score temporarily. Spacing applications 60 to 90 days apart tends to limit the damage while still letting you build the trifecta within a year.
Once your three cards are active, maintenance matters as much as the initial setup. Put quarterly category activations and annual credit resets on a recurring calendar reminder, review your full setup once a year, and check whether a card’s benefits still match how you actually spend before paying another year’s fee on autopilot.
Sample Math: Chase Trifecta vs. Amex Trifecta for a Real Spender
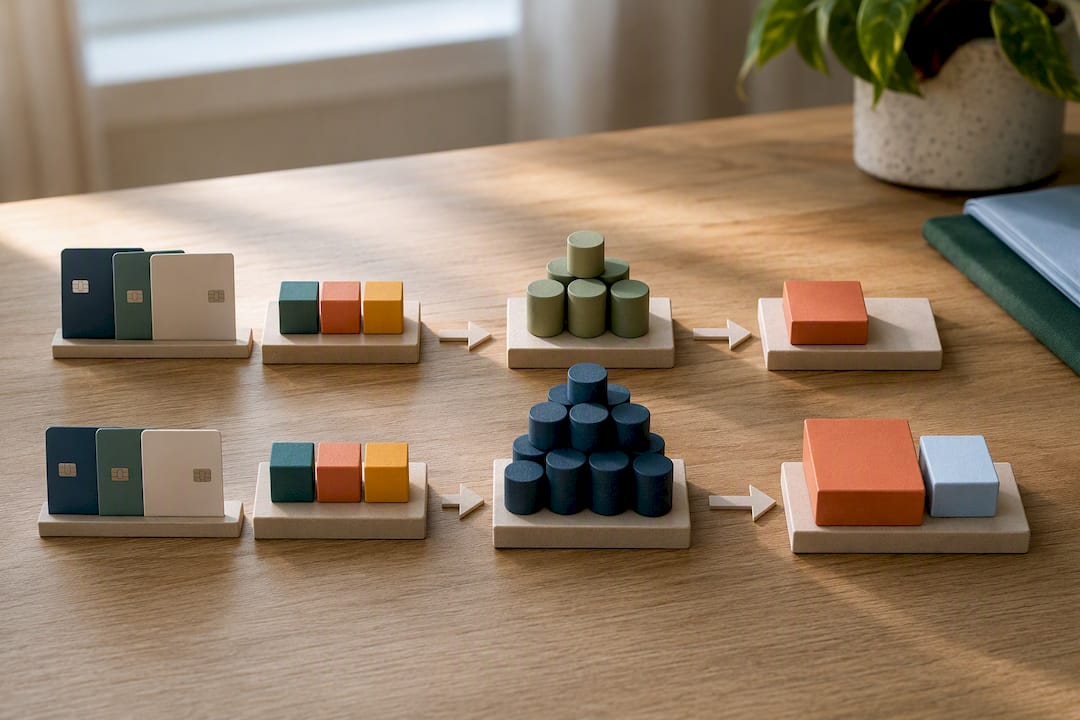
Mika L., who covers rewards strategy for Savings Grove, built out two comparison scenarios using a moderate U.S. traveler profile: someone spending roughly $3,000 a month with a realistic mix of dining, groceries, travel, and everyday purchases. The goal wasn’t to crown a universal winner. It was to show how fee-offset math changes the answer depending on where your spending actually concentrates.
The Chase setup wins on cost efficiency almost every time for this spend level. The Amex setup earns more raw points and can deliver a higher redemption ceiling for someone who eats out often and travels through premium cabins, but only if the statement credits actually get used. Skip even half of Platinum’s credits, and the Amex trifecta’s net cost climbs well past what the extra points are worth for a moderate spender.
For a deeper look at how point multipliers translate into dollar value, the points math breakdown walks through the conversion step by step, and the premium tier benefits guide covers which credits are worth chasing versus which ones quietly go unused every year.
When Is a Trifecta Overkill?
Not everyone needs three cards to optimize rewards, and pretending otherwise does readers a disservice. If your monthly spending is under $1,500, if you know you won’t track quarterly categories or statement credits, or if you tend to open and close cards frequently, a trifecta usually costs you more in mental overhead than it returns in points.
A single premium card paired with one no-fee catchall card covers most of the same ground with a fraction of the tracking. A rotating-category card alone can work well if your spending genuinely shifts with the seasons Chase and Discover choose to bonus.
Automate what you can. Set your statement credits and category activations on a recurring calendar reminder, and review your setup once a year instead of constantly. Rewards points earned by a card sitting forgotten in a drawer aren’t worth the annual fee, no matter how generous the sign-up bonus looked.
— Mika L.
Track Your Trifecta With Savings Grove’s Tools
Building a trifecta is one thing. Keeping it profitable year over year is another, and that’s where most people quietly lose money by forgetting a credit or missing a category activation. Updated card comparisons and points-math breakdowns are maintained specifically to help recalculate net value whenever an issuer changes a fee or a transfer partner adjusts its chart.
Use the category spending benefits guide to match your actual spending against the right bonus categories before you apply for anything new, and check the Chase 5/24 breakdown if you’re unsure where you stand before submitting an application. Both resources get refreshed monthly alongside the rest of Savings Grove’s credit card coverage, so the numbers you’re working from reflect current terms rather than a rate that expired last year. Start by pulling your last three statements and mapping them against one of these guides. That’s the same first step behind every trifecta calculation on these guides.
Sources
- Chase Trifecta: Ultimate Guide To Maximizing Rewards — Forbes Advisor
- Best 3-Card Credit Card Setup for 2026 — CardStack
- Why you need the Chase Trifecta in your wallet — The Points Guy
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
FAQ
What Is a Credit Card Trifecta?
A credit card trifecta is a set of three complementary credit cards, usually from one issuer, that pool rewards into a single currency to cover more spending categories and unlock better redemptions than any single card alone.
Is the Chase Trifecta or Amex Trifecta Better?
The Chase trifecta costs less overall and works better for simplicity and flexibility, while the Amex trifecta earns more in dining, grocery, and premium travel categories but carries significantly higher combined annual fees.
Do I Need Good Credit for a Trifecta?
A credit score in the high 600s can qualify for entry-level cards in either trifecta, but scores near 720 or above improve approval odds for premium cards like Sapphire Reserve or Amex Platinum.
How Does Chase’s 5/24 Rule Affect a Trifecta?
Chase generally denies applicants who’ve opened five or more personal credit cards across any issuer in the past 24 months, so it’s smart to apply for Chase cards before that count climbs.
Can Savings Grove Help Me Calculate My Own Trifecta Value?
Yes. Savings Grove publishes updated card comparisons and points-math guides that help you map your spending to the right cards and calculate net annual value after fees and credits.